
Investments
Investing with SuperLife
Step 1: Enter your member number in the first box. You’ll find this in your Welcome Letter or Member Certificate.
Step 2: Fill in your date of birth, last name, and email address. Make sure your last name matches our records exactly (including any hyphens) and double-check your date of birth.
Step 3: Under Login details, create a username and password. These will be your credentials for accessing the member portal.
Step 4: Press "Submit" to confirm your registration.
Step 5: Check your email inbox for a verification message from SuperLife. Open the email and follow the instructions to verify your email address.
Step 6: Once verified, you can log in using your new username and password.
SuperLife Invest is our most flexible investment and savings option. You decide how much you invest, when you invest and when to make a withdrawal. Our broad range of investment options lets you tailor an investment strategy to suit your needs, and our fees are among the lowest in the market.
To learn more, read the SuperLife Invest product disclosure statement or visit our Returns and Fees page.
It's easy to sign up online. Click here to get started.
Regular savings / contributions
- You can save by making regular payments and change (or stop) the amount you save at any time. Please note that changes to regular savings will be subject to the rules for the scheme you invest in - for example, rules relating to minimum contributions.
- Regular savings can be set up via your online login, by selecting "Add contributions" in the menu. These are made by direct debit from your bank account. Contact Us to learn more, or visit our Forms page ("Contributions and withdrawals") if you prefer to print and send a form to us.
Lump sum payment / investment
- You can make a lump sum payment into your account at any time using internet banking by selecting ‘SuperLife (Invest & KiwiSaver)’ as the payee or by using the bank details below.
Alternatively, if you are a member of SuperLife Invest, you can log in to your account and set up a lump sum contribution, made via direct debit.
By Internet Banking
Bank name: ASB Bank
Account name: SUPERLIFE WORKPLACE SAVINGS SCHEME
Account number: 12-3244-0039562-00
Payment reference: SuperLife Member number
Payment code: Your surname
Please email superlife@superlife.co.nz to inform us of the transfer.
If you want to choose a specific investment strategy for your contribution, please complete a contribution form for SuperLife Invest, which tells us when and how you would like the money invested.
SuperLife is obliged to meet the requirements of the Anti-Money Laundering and Counter Financing of Terrorism Act and so we have to collect and hold on file verification of identity and address. The details of what is required can be found here.
As part of our commitment to sustainability and improving member services, we no longer print quarterly or monthly statements. Electronic delivery is faster, safer, and more environmentally friendly. The SuperLife member portal gives you secure access to your information whenever you need it. Login at my.superlife.co.nz
If you’ve chosen the printed option, you’ll receive an annual printed statement by post. Quarterly and monthly statements are only available online or by email.
Changing your investment strategy (including fund switches)
You can change your investment strategy for existing savings (i.e. fund switch to move money between funds) and/or future savings at any time online free of charge. Log in to My SuperLife and select "Change strategy" to get started.
If you prefer to complete a form and send it to us, simply download the "Change investment strategy" form from this page.
Investment basics
To help you make informed investment decisions, we have a range of online resources for you to draw from. View our articles and guides, recent newsletters and information about upcoming investment seminars across New Zealand.
The government’s Sorted website also includes a number of useful tools on KiwiSaver, investing and savings.
Income assets include cash and bonds (“fixed interest”). With cash, we would expect positive returns, but lower than the returns for other assets over the long term. Investing in cash is suitable when money may be required in the short term. With fixed interest, we would expect positive returns that are higher than the returns for cash over 3–5 years, but at times returns can be negative over the shorter term. Investing in fixed interest is suitable when money may be required in the medium term.
Growth assets include shares and property. With shares and property, we would expect positive returns that are higher than the returns for cash and fixed interest over the long term, but at times returns can be negative over the short to medium term. These negative returns can be quite large. Investing in shares and property is suitable when money can be invested for the long term.
We believe that an index-tracking approach to investing will deliver better long-term results. Index-tracking investing means we will either invest in a fund designed to track an index or in a number of assets for the long term. We do not think that constantly changing our investments (that is, trading regularly and seeking short-term gains), consistently adds value to investors.
Diversification (not putting all your eggs in one basket) is one of the most effective ways to smooth out the highs and lows in your investments.
By investing across different asset types (cash, bonds, property, and shares) and markets, you’re not relying on one to do all the work. Spreading your investments delivers steadier growth over time because different types of investments can react differently to market movements.
How you mix your investments will depend on your goals, how long you plan to invest, and how comfortable you are with the ups and downs along the way. These factors will help you tailor your investment portfolio.
People with a longer investment timeframe or a higher tolerance for short-term ups and downs may be comfortable holding more growth assets (property and shares), while those with shorter timeframes often choose to hold a larger share of income assets (cash and bonds).
Everyone’s situation is different, so the right balance will depend on your goals and circumstances.
A 'core-niche' approach - One way to balance long-term stability with exposure to particular regions or sectors is using a core and niche approach.
In this approach, your core portfolio consists of your key long-term investments that typically make up the majority of your overall portfolio – often 80% or more. Your niche investments are smaller, more dynamic positions, such as sector-specific or thematic investments, allowing you to take advantage of emerging trends or market opportunities.
Investors can apply this kind of thinking by combining diversified funds as a core portfolio and adding selected single-sector funds as niche tilts.
Investing involves risk. We recommend you seek professional assistance from a licensed Financial Advice Provider before making any investment decision.
Understanding your investment returns
SuperLife generally credits the investment returns to members’ accounts on a daily basis (a valuation day). Each valuation day, we calculate the amount of the investment earnings for each investment fund since the previous valuation day. We then allocate that amount across the members’ balances, for the members who had a holding in that fund at the end of the day. The allocation is made proportional to the value at the beginning of the valuation period, less any payments subsequently made. There are no reserves or smoothing mechanisms applied. The total return earned on the investments of the fund, whether positive or negative, is what is credited each valuation day.
You can read more about the allocation of investment returns by clicking here.
The New Zealand tax laws are complex because investment earnings are taxed in one of three ways and not all investment earnings are taxable. An explanation of the tax treatment of earnings is here.
With New Zealand shares, for example, tax is only payable on the dividends we receive. The market movement is not taxable. So if we receive a 6% dividend and the market goes up by 10%, your total return is 16% but you only pay tax on 6%. Likewise if the market goes down by 10%, your total return is -4% (i.e. 6% dividend less 10% market downturn) but you still pay tax on the 6% dividend. The same applies for Australian shares. Over the long term we expect the share market to go up, so you will pay less tax than you would if the total return was taxable, but over short periods you get strange looking results.
Overseas shares are more complex. With overseas shares we pay tax on 5% of the assets as if we always get a 5% return. This is irrespective of what return we get. Again long term we expect to pay less tax than your PIR rate but when the markets go down we still have to pay tax.
Annual PIE Tax Certificate
The Annual PIE Tax Certificate is sent to members of the SuperLife schemes. It shows the amount of tax you paid on taxable income earned by the schemes for the year ended 31 March.
You will receive a certificate even if you left a SuperLife scheme during the year ended 31 March.
The SuperLife workplace savings scheme and each fund in SuperLife Invest is a portfolio investment entity (PIE), which means that tax has already been calculated and paid to Inland Revenue using your prescribed investor rate (PIR).
Your PIR is shown on the certificate. You can also work out your PIR by using the Inland Revenue’s PIR calculator.
Your PIR can be 0%,10.5%, 17.5% or 28%. You don’t have to do anything if the PIR shown on the certificate is correct, as your tax has already been paid on the taxable portion of your investment income by adjusting your balance in the relevant fund(s).
You may need to complete a tax return if the PIR we held for you was incorrect. If you are not sure, you should consult your accountant or tax adviser.
- Change your PIR online at my.superlife.co.nz
- Email superlife@superlife.co.nz (include your name, date of birth, SuperLife member number or your IRD number).
- Call us on 0800 27 87 37 if you need help with your PIR.
The amount of tax paid is calculated based on your PIR at the end of the period.
You can find more about PIRs and how to work out your rate on Inland Revenue's website.
Where an account is jointly held, each holder must advise SuperLife of their IRD number and PIR. SuperLife will use the higher of the two PIRs when calculating the tax payable on the account.
If you have a 0% PIR, you are required to include the information from the Annual PIE Tax Certificate in your tax return. If you are not sure, you should consult your accountant or tax adviser.
Insurance
*
SuperLife offers four types of insurance:
- Life insurance - Provides your beneficiaries (for example, children or spouse) with a lump sum amount in the event of your death. The benefit can also be paid should you become terminally ill.
- Total and permanent disability insurance - Allows for an early pay out of your life insurance if you suffer illness or injury that leaves you totally and permanently disabled.
- Disability income protection insurance - Helps protect you from the loss of income through a severe disability that prevents you from working for an extended period.
- Medical insurance - Insures you and/or your family against part or all medical expenses.
The life and disability insurance solutions are provided by Fidelity Life, and medical insurance is provided by UniMed.
If you already have insurance with SuperLife, or belong to a SuperLife workplace savings scheme offering insurance benefits, get in touch with the SuperLife team at 0800 27 87 37, or email us superlife@superlife.co.nz
Life insurance
The amount charged depends on factors such as:
- gender, age and health;
- whether or not you smoke;
- the premium basis you choose i.e. the 1 or 5 year option; and
- the amount of cover you take out (as the premium rates relate to each $1,000 of cover you choose)
A lump sum will generally be paid if you die, for any reason, except if:
- you have not paid for the insurance; or
- you did not complete the application form accurately.
There are also special provisions that apply in times of war.
If you die, SuperLife will pay your life insurance to the person or people you nominate (i.e. beneficiaries). If you nominate more than one person, you need to state what proportion each person should receive. SuperLife is required by law to pay the beneficiaries you nominate, so you need to make sure your nomination is kept up to date. If you want to edit, remove or add beneficiaries to your life insurance you will need to fill in an update beneficiary form or do it online.
If you don’t make a nomination, SuperLife must pay the insurance to your estate.
SuperLife can delay payment if it is aware that your benefit might be subject to a claim under the Property (Relationships) Act 1976.
SuperLife will need copies of your death certificate before it pays the insurance money.
In most cases an increase to your insurance cover (“benefit”) requires you to provide medical details.
Call our team on 0800 27 87 37 to discuss your situation.
When you first apply for life insurance cover and before it is confirmed, the insurer has agreed to cover you for “accidental death” for the amount you choose for up to three months from the date SuperLife receives your application form.
This accidental death cover will cease within the three month period, when you are advised by SuperLife of the terms on which the insurer has accepted (or declined) your application.
All life insurance costs more as you get older, and SuperLife is no different.
The 5-year option means the premiums that you pay for your insurance stays the same for 5 years rather than increasing each year.
This means, instead of a smaller annual increase, your premiums will stay the same for 5 years but increase more substantially at the end of this period. Whether you choose the annual or 5-year option, overall, you will pay about the same.
For an additional premium, you can extend your life insurance benefit so the cover can be paid if you become "totally & permanently disabled" (TPD) before age 65. You are not required to have the same amount of TPD cover as for death - it can be less.
The insurance policy gives the legal definition of "total & permanent disablement". The main features are:
- You are sick or injured;
- You are away from work for six months in a row or more;
- You must have a full medical examination;
- The insurer decides, either:
- You are incapacitated to the extent that you are never likely to work in a job for which you are reasonably qualified by education, training or experience, or
- You have lost the use of two limbs, or you are blind (or have lost one limb and are blind in one eye).
The insurer decides if you are "totally & permanently disabled". As a result, you will need to supply the insurer with medical evidence of your disablement. If the insurer needs more information, it can arrange for you to be examined by its own medical advisers.
Disability insurance
The amount charged for disability insurance depends on factors such as your sex, age, job category, health, benefit period and the level of the benefit.
You can choose any benefit level you want between the minimum under Rule 1 and the maximum under Rule 2.
- Rule 1: It must be at least $5,200 a year ($433 a month);
- Rule 2: It cannot be more than $55 for every $100 of your before-tax pay. Remember the benefit paid is tax free.
The insurer decides if you are totally disabled and will get a benefit. You will need to supply the insurer with medical evidence of your disablement. If the insurer needs more information, it can arrange for you to be examined by its own medical advisers. The insurer will meet the cost of this.
SuperLife’s insurance policy provides the legal definition of "totally disabled". The main features are:
- You are sick or injured;
- You have been away sick or injured for the whole of the "waiting period" (time between your first day off work and the day your disability insurance starts);
- A qualified doctor is in charge of your treatment;
- The insurance company considers that (i) for office workers, “travellers” and technicians - you can’t do your own job, or (ii) for light & heavy manual workers, trades and hazardous occupations - during the first two years, you can't do your own job; and after the first two years, you are incapacitated to the extent that you are unlikely to work in a job for which you are reasonably qualified by education, training or experience.
Once the insurer has determined that you are disabled, SuperLife will start paying your benefit monthly in arrears.
Each year, the insurer will increase the amount SuperLife pays you, in line with increases in the cost of living (CPI) to a maximum of 5% a year.
You must keep paying for your insurance premiums during the "waiting period" you have chosen (time between your first day off work and the day your disability insurance starts). If you are not getting paid by your employer, the cost can be rolled up and come out of the first month's benefit payment (if you get better and go back to work, that cost can then come out of your pay). You can also use money that you have in your SuperLife savings voluntary account to pay those costs.
The benefit will stop before the end of the “benefit period” or when you are no longer "totally disabled" - whichever happens first. You are classified as no longer “totally disabled” when:
- you start working again; or
- a qualified doctor is no longer looking after you; or
- the insurer, based on medical evidence, concludes that you are no longer disabled; or
- you die.
The insurance company offers a special deal to encourage you back to work. If you go back to your original employer but can't earn as much (because of your disability) your benefit won't stop. It will be reduced by the proportion that your new lower pay bears to your old higher pay. This special deal is called a "recovery benefit". It could last for up to two years (but not past the end of your benefit period).
There are some exceptions to be aware of. A benefit will not be paid if:
- you stopped paying premiums; or
- you intentionally injure yourself; or
- you stopped work due to pregnancy or childbirth (but a benefit may be payable if you cannot return to work due to complications from pregnancy or childbirth); or
- your income ceased before you become ill or disabled; or
- special circumstances exist - for example, there are particular provisions which apply in times of war.
This is the period between your first day off work and the day your disability insurance starts.
You can choose your waiting period (one, three or six months). You should allow for any sick leave you are entitled to and consider how long you can afford not to have an income if you are disabled; the longer the waiting period, the cheaper the cost of cover.
You can choose the maximum number of years that the disability insurance benefit is paid to you while you are disabled - this is called the "benefit period". Your choices for the benefit period are:
- two years;
- five years, or
- until you reach age 65.
The benefit period starts when you receive the first disability insurance payment at the end of the waiting period. The disability insurance payments will stop before the end of the benefit period if the insurer determines that you can start work again.
In most cases an increase to your insurance cover (“benefit”) requires you to provide medical details.
Call our team on 0800 27 87 37 to discuss your situation.
SuperLife lets you replace some of the income you may lose from being disabled or sick. In some situations, you might have an “agreed amount” of insurance for example, in cases where your income varies a lot from year to year. This will need to be organised at the time your insurance policy is set up.
If you leave employment and don’t have a job to go to, you can continue as a SuperLife member but will need to arrange an “agreed amount” of insurance with the insurer.
With the exception of an “agreed amount”, your cover cannot be more than 55% of your before-tax regular pay at the date the benefit entitlement arises even if your original cover is higher.
Your actual benefit paid will also be reduced if you get an ACC pension or income under other disability or accident insurance. The SuperLife insurance will only top up the money you get from those sources, i.e. it will not exceed the disability insurance benefit otherwise payable.
SuperLife for Employers
About us
Choosing SuperLife means:
- You can tailor the rules around the contributions and benefits, and create a plan designed for your business.
- It's more than just superannuation; we can add other benefits to your plan, such as insurance and KiwiSaver.
- We take care of the administration (e.g. collections and payments) and ensure that you and your employees receive regular important information including market updates.
- We are a master trust. Through SuperLife, your employees can choose investment options that suit them. SuperLife brings the advantages and lower costs of group purchase to your employees.
- Our savings, benefit payment and investment options offer a significant amount of choice, flexibility and value to your employees.
Superannuation Master Trust
The SuperLife Superannuation Master Trust was previously known as the ASB Superannuation Master Trust. Smartshares acquired the scheme in 2022 and the transition of the scheme from ASB to Smartshares is now complete.
FAQs and other information for SuperLife Superannuation Master Trust members and employer groups can be found here.
Understanding my Annual PIE Tax Certificate
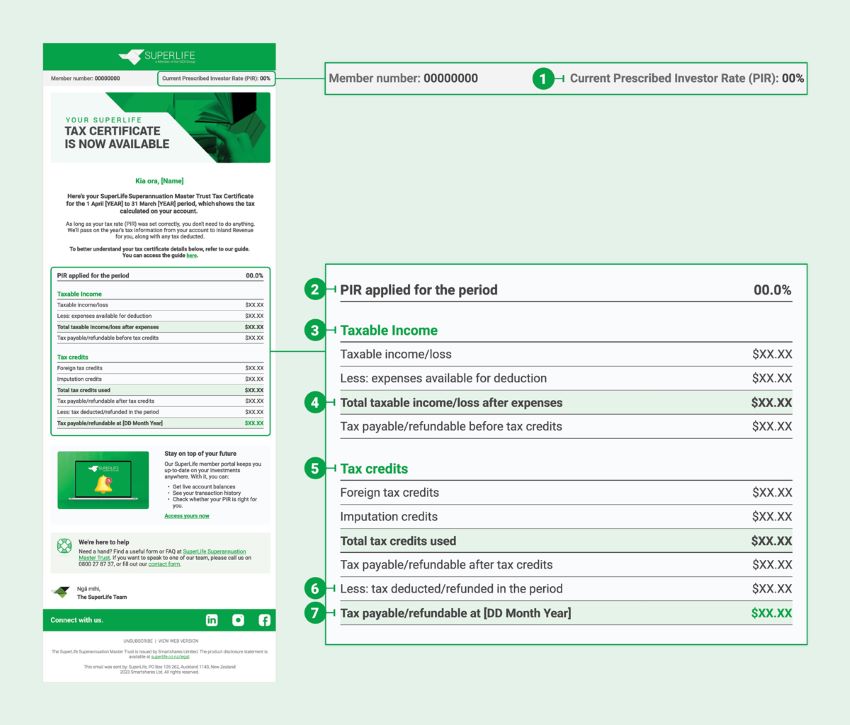
- Your Prescribed Investor Rate (PIR) sets how much tax you pay on the taxable income from your investment. This is the PIR we currently have on record for you.
You can set your PIR rate at your profile page on the Member Portal or contact us.
You can work out your PIR rate by visiting the Inland Revenue website. - This is the PIR that has been used to determine your tax for the year ended 31 March.
- This is the income you’ve earned from your investment that’s subject to tax. The total taxable income/loss may not match your total returns, as not all return components are taxable.
- Your administration fees are expenses that can be deducted from your taxable income, which reduces the amount of tax you have to pay.
- Tax credits represent any tax that has already been deducted from your taxable income, or paid before it’s received by the fund. These credits reduce any tax you need to pay on your investment’s taxable income.
- Tax deducted/refunded highlights any tax that was paid on, or refunded to, your taxable income/loss during the last 12 months. These can occur when you make a withdrawal or switch between funds.
- This is your final amount of tax payable or refundable.
NZ Super
Eligibility and rates
You may qualify for NZ Super If you:
- are age 65;
- either:
- a New Zealand citizen
- are a permanent resident
- or hold a residence class visa
- are ordinarily resident in New Zealand, the Cook Island, Niue, or Tokelau when you apply
- have lived in New Zealand for at least 10 years since age 20;
- have lived in New Zealand, the Cook Islands, Niue or Tokelau (or a combination of these) for at least 5 years since age 50.
Residence in a country with which New Zealand has reciprocal social security arrangements (like Australia and the UK) counts as residence in New Zealand.
When we say ‘you live’ or ‘you’ve lived’, we mean you normally live in NZ, the Cook Islands, Niue or Tokelau and that’s where your home is.
You may qualify for NZ Super with less than 10 years residence if you have migrated to New Zealand from a country that New Zealand has a social security agreement with.
Click here for more information on NZ Super.
The NZ super benefit is linked directly to the national average wage and is reviewed each year (1 April). The current level is 66% of the net national average wage.
The pension is taxed as income in the normal way under the PAYE system.
There are no income or asset tests applied to NZ Super. However, if one partner of a couple qualifies and the other does not, both may receive the benefit, but an income test applies in respect of the benefit paid to the partner that does not qualify in their own right.
However, entitlements to an overseas social security pension (like the UK’s Basic State Pension) but not work-related, employer-provided pensions, reduce the New Zealand pension by the equivalent amount.
Please check the Work and Income website for full details of the most-recent superannuation rates.
Investing 101
Dealing with market volatility
Periods of volatility in global share markets and negative returns can understandably create uncertainty for many investors. These fluctuations are usually driven by a combination of factors, including geopolitical events, movements in interest rates, changes in the economic outlook and shifting investor sentiment.
While market downturns can be unsettling, it is important to remember that volatility is a natural part of investing. Share markets are constantly on the move, both up and down. History shows us that over the longer term, markets usually recover from short-term declines.
Although shares are volatile and occasionally deliver negative returns, they have historically offered the highest potential for long-term growth. By staying invested, you position yourself to benefit from the compounding returns that shares can deliver over time.
Market uncertainty is a constant – nobody can predict exactly when markets will rise or fall, or which markets or assets will perform best. This is why appropriate diversification (i.e. not having all your eggs in one basket) is such a cornerstone of long-term investing. Different assets and markets can react differently to market fluctuations. This means holding a range of investments, such as local and global shares, fixed interest and other assets can help offset losses, reduce your portfolio’s volatility and cushion the impact of downturns.
We offer a range of diversified funds (such as the SuperLife Income, SuperLife Conservative, SuperLife Balanced and SuperLife Growth Funds) that have been created to serve this purpose. They contain a mix of income and growth assets, potentially providing some protection against large downward movements in share markets.
While a decline in the value of your investments can understandably be concerning, making decisions based on short-term market fluctuations can have a negative impact on your long-term returns. For instance, selling during a market dip may lock in losses and prevent you from benefiting from any potential rebound as markets recover. It is important to consider when you will need to draw on your investments. If you have a shorter investment timeframe – meaning you may need to access your money sooner – you might want to consider a higher allocation to lower-risk investments, such as cash and fixed interest (bonds), which are less exposed to market fluctuations.
This is why it may be appropriate for investors near, or in, retirement, and others with a short-term investing timeframe, to have a mix of cash to cover immediate expenditure, fixed interest for medium term expenditure and shares for longer term expenditure.
On the other hand, if you’re investing for the long term, you’re better positioned to ride out market ups and downs. Shares have historically delivered higher returns over time, but they can experience short-term fluctuations. By staying invested through different market cycles, you give your portfolio the opportunity to recover from downturns and benefit from long-term growth.
Periodically reviewing your portfolio is a good way of ensuring it remains well-diversified and has a mix of assets which aligns with your goals, investment time frame and risk profile. These factors – rather than short-term market fluctuations – should guide your investment decisions.
Continuing your regular savings plan during periods of market volatility can be beneficial. If you are making regular contributions to your portfolio or KiwiSaver, a fall in markets means you can invest at lower prices. Picking the best time to invest is a lot easier said than done. For most investors it is better to invest regularly. This is called a “dollar cost averaging” approach. By investing on a regular basis, regardless of the price, you average out market fluctuations over time. This also lets you focus on the average return over the long-term and not react to short-term events.
Markets can continue to be volatile for some time. The timing or extent of any ‘turnaround’ after a period of negative returns is unpredictable, but history shows that markets do typically recover from downturns over time. In the meantime, it is important to maintain a diversified portfolio and stay focused on your long-term investment goals.